 Gold Prices Rise in the UAE as Dollar and Yields Ease
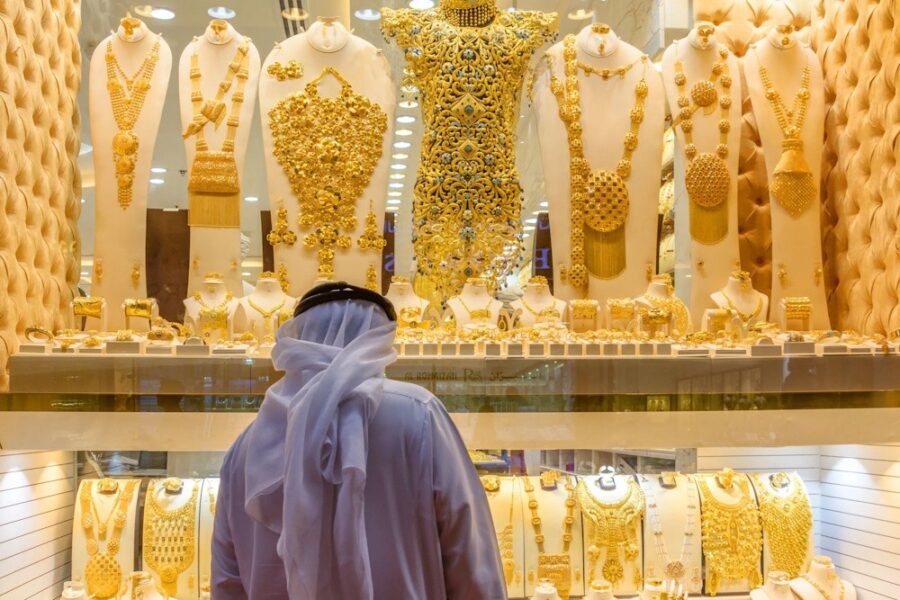
Gold prices in the UAE experienced another increase on Thursday morning, marking a strong start to September and elevating costs for residents looking to purchase jewellery or invest in the metal. The 24-karat variety was priced at Dh532 per gram at 8.56 am on September 3, reflecting an increase from Dh528.25 on Wednesday, marking a daily rise of Dh3.75. The 22-karat variety rose to Dh492.50 from Dh489.25, indicating an increase of Dh3.25. Prices have shown a steady increase since the beginning of the month. The 24-karat rate has increased from Dh522 on September 1 to Dh528.25 on September 2, and subsequently to Dh532 on September 3, culminating in a three-day rise of Dh10 per gram. The 22-karat variety experienced an increase from Dh483.25 to Dh489.25, subsequently rising to Dh492.50 over the same period. Meanwhile, the 21-karat gold increased from Dh463.50 to Dh472.25, while the 18-karat experienced a rise from Dh397.25 to Dh404.75. The increase in retail rates in the UAE aligns with a recovery in international gold prices after a drop to around $4,285 per ounce. The rebound follows a correction from the nearly $4,700 peak reached in late August, when comments from Federal Reserve Chair Kevin Warsh at Jackson Hole led markets to increase expectations of higher US interest rates.
Treasury yields and the dollar subsequently increased, exerting pressure on gold. Conditions have since become more favourable, with the 10-year US Treasury yield declining to approximately 4.78% after approaching 5%, while the dollar index has decreased to the 99.1 to 99.2 range. Tran stated that the alteration in bond yields has been pivotal to the recovery, as the pressure on gold diminished once yields and the dollar ceased their ascent. Lower prices have also drawn a portion of buyers back into the market. Weaker US private-sector employment data acted as an additional supportive factor; however, the immediate response in gold prices was limited. ADP data revealed that the US private sector saw an addition of 38,000 jobs in August, which was below the expected figure of 48,000. Manufacturing experienced a contraction of 17,000 jobs, while professional and business services observed a decrease of 16,000 positions. Investors are presently awaiting the publication of official nonfarm payroll data to obtain a clearer insight into the dynamics of the US labour market.
New York Fed President John Williams stated that there are presently no distinctly clear signals to determine if additional tightening of monetary policy is required, rendering the decision for September dependent on upcoming economic data. Interest-rate risk remains a significant consideration, with current market assessments indicating an estimated 62% probability of a further 25-basis-point hike by the Federal Reserve in September. Headline and core PCE inflation recorded at 3.7% and 3.3% year-on-year, respectively, persist in surpassing the Federal Reserve’s 2% target. Geopolitical uncertainty remains a substantial element impacting gold, though its effects are not consistently one-dimensional. The US-Iran conflict may elevate the demand for gold as a safe haven, while rising oil prices stemming from regional tensions could heighten inflation expectations and maintain elevated US interest rates. “The current recovery therefore reflects a combination of dip-buying demand, easing yields, a slightly weaker dollar and hedging against geopolitical uncertainty,” Tran stated. The immediate trajectory of gold is set to be significantly influenced by upcoming US employment and inflation data, as well as signals from the Federal Reserve.
Tran observed that the decrease in Treasury yields alongside a weakening dollar was creating favourable conditions for gold. However, further evidence would be necessary to illustrate that inflationary pressures were easing and that the US labour market was consistently weakening. Central-bank purchasing and investment appetite continue to provide support, extending beyond the recent price fluctuations. Central banks accumulated a net total of 289 tonnes of gold during the second quarter, whereas global gold exchange-traded funds attracted an additional $3 billion in July, after experiencing two months of consecutive outflows. “Over the medium term, I maintain a cautiously optimistic outlook on gold. “Demand from central banks, investment flows and concerns over U.S. public debt continue to provide meaningful support,” Tran stated. The rebound from approximately $4,283 to $4,285 has alleviated some of the recent selling pressure, while the return above $4,400 has enhanced gold’s short-term position. Tran stated that the action was still inadequate to validate a lasting upward trend, with US employment, inflation, and interest-rate expectations anticipated to remain as primary influences on prices in the near future.